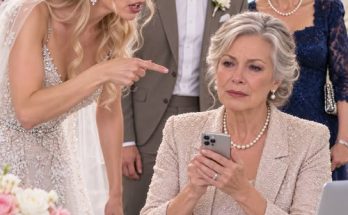
Part 1: My Daughter-in-Law Humiliated Me at Dinner—Then My Son Learned I Had $800,000 He Never Knew About
My daughter-in-law told me to disappear into my bedroom while her guests were still sitting at the dinner table. Then she turned toward my son and said, “Logan, are you going to do something about your father?” I waited for him to defend me, but he stared into his glass and whispered, “Dad, maybe you should give us some space.” That night, I decided to leave. Neither of them knew that I had nearly $800,000 in investments—or how much of their comfortable life depended on my financial support.
My name is Albert Higgins. I’m sixty-eight years old, a retired senior accountant, and a widower.
Six years earlier, when my wife Margaret passed away, Logan invited me to live with him and his wife, Chelsea, in Dallas, Texas.
At first, I was grateful.
After forty years of marriage, returning to an empty house felt unbearable. I missed Margaret’s laughter, her morning coffee, and the way she always left the porch light on when I worked late.
Logan assured me I would always have a place with his family.
For a while, I believed him.
I helped with groceries, cooked dinner several nights a week, and occasionally picked up supplies for Logan’s renovation business.
Then Chelsea began making little comments.
“Albert, would you mind eating in the kitchen tonight? We’re having friends over.”
A few months later, she asked me to stay upstairs whenever her coworkers visited.
Eventually, she suggested I use the back entrance so guests wouldn’t see me walking through the living room.
Each request seemed small enough to ignore.
Together, they made me feel like an unwanted stranger.
What Chelsea didn’t know was that I had spent decades saving and investing carefully. My retirement income covered my needs, and my investment portfolio had grown to approximately $800,000.
I wore old sweaters because they were comfortable, not because I couldn’t afford new ones.
More importantly, I had quietly helped Logan and Chelsea build the lifestyle they enjoyed.
When Logan’s renovation company needed additional financing, I pledged part of my investment portfolio as collateral for a business credit line.
When their house required major repairs, I provided a documented family loan of $186,400.
I also established an account to help with household expenses.
I never demanded praise.
I only hoped my son understood that I was helping because I loved him.
That Monday evening, Logan invited several coworkers to dinner.
I spent the afternoon preparing stuffed mushrooms, his favorite childhood appetizer. Margaret used to make them whenever he brought home a good report card.
When I carried the tray into the dining room, Chelsea barely glanced at it.
“Albert, please stop hovering.”
I stepped aside.
A few minutes later, she approached again.
“Why don’t you stay in your room tonight?”
I looked at her.
“I was just bringing out the food.”
“We have company. I don’t want everyone feeling uncomfortable.”
Several guests had heard her.
Then she turned toward Logan.
“Are you going to handle this?”
The room became painfully quiet.
I looked at my son.
He stared at his drink.
“Dad,” he finally murmured, “maybe you could give us some space.”
I set the serving tray down.
“Of course.”
Nobody stopped me as I walked upstairs.
Before sunrise, I packed two suitcases containing my clothes, documents, photographs, and laptop.
I left my house key on the kitchen counter.
There was no note.
No argument.
I simply walked away.
The following morning, I met with a contract attorney named Fiona Cartwright.
She examined the financial agreements I’d signed over the previous six years.
“What would you like to accomplish, Mr. Higgins?”
“I want to separate my finances from my son’s household and business.”
She reviewed the documents carefully.
“We can begin that process, but everything must follow the contractual requirements.”
“That’s exactly what I want.”
Over the next three weeks, Fiona coordinated the necessary notices with the bank and investment custodian.
I wasn’t taking money that belonged to Logan or Chelsea.
I was ending financial arrangements I’d never intended to maintain forever.
At precisely 8:30 one morning, three envelopes were delivered to their house.
The first concerned the collateral securing Logan’s business credit line.
The second concerned repayment of the family renovation loan.
The third terminated their access to the household investment account.
I was sitting in Fiona’s office when my phone began ringing.
Logan.
Then Chelsea.
Then Logan again.
I let the calls go unanswered.
For six years, they’d treated me like a burden while depending on financial support they barely acknowledged.
Now they were about to discover what that support had actually meant.
Fiona placed one final document in front of me.
“Albert, there’s something else we need to discuss.”
I looked at the page.
It was a four-year-old investment statement.
At the bottom appeared a figure Logan had never bothered to examine.
$803,417.29.
And beside the account balance were two words that would change everything.
Sole owner.
Part 2: My Son Called Me Selfish for Cutting Off His Money—Then He Discovered the Truth About My $800,000
My son called seven times after receiving the three envelopes. His wife called twice, and an unfamiliar number appeared between their attempts.
I watched my phone light up on Fiona Cartwright’s conference table.
“You’re allowed to answer,” my attorney said.
“I know.”
“You’re also allowed to wait.”
I turned the phone facedown.
For six years, I’d been available whenever Logan needed money, advice, or someone to solve a problem. Yet when I needed him to defend my dignity, he’d looked into his drink.
Fiona reviewed the documents we’d delivered.
The first notice confirmed that my investment securities would no longer secure Logan’s business credit line. His bank had given him thirty days to arrange replacement collateral or refinancing.
The second demanded repayment of the $186,400 renovation loan under our written agreement.
The third ended Logan and Chelsea’s authorization to use the account I’d established for household expenses.
“Everything has been reviewed for compliance with the agreements,” Fiona assured me. “You’re not taking their property. You’re ending financial support that belongs to you.”
I nodded, although the situation still hurt.
“I never wanted to make my son afraid of losing everything.”
“Then why are you doing this?”
“Because I finally realized I was afraid of losing him if I stopped paying.”
Fiona’s expression softened.
“Those are two different problems, Albert.”
That evening, I returned to my rented apartment in Irving. It had a small kitchen, two chairs, and a bedroom with bare white walls.
There were no family photographs yet, but nobody had asked me to hide in it.
The next morning, Logan called again.
This time, I answered.
“Dad? Thank God. Where are you?”
“I’m safe.”
“Why did you disappear?”
I looked toward the window.
“You heard Chelsea tell me to leave the dining room.”
“That wasn’t the same as asking you to move out.”
“No. But it made something clear.”
He sighed.
“Can we please talk about these notices?”
“Of course.”
“The bank says your investments were securing my business loan.”
“That’s correct.”
“I didn’t realize you could withdraw them.”
“You signed the agreement, Logan.”
“I signed a hundred papers that day.”
“And I explained what mine meant.”
Silence followed.
Then he asked about the renovation loan.
“You said you wanted to help us.”
“I did. That’s why I lent you the money.”
“But we’re family.”
“Being family doesn’t turn a signed loan into a gift.”
His voice tightened.
“Chelsea thinks you’re punishing us.”
“I’m protecting my retirement.”
“By putting my company at risk?”
“Your company was already relying on assets it didn’t own.”
I heard Chelsea speaking in the background, asking him to hand her the phone.
“I’m not ready to speak with her,” I said.
“Dad, she wants to explain.”
“Then she can wait.”
Logan sounded stunned.
I’d rarely refused either of them anything.
Finally, I suggested meeting alone at a café the following afternoon.
He agreed.
When he arrived, his shirt was wrinkled, and he looked as though he hadn’t slept.
“I was worried about you,” he said.
“I believe you.”
“Then why didn’t you call?”
“Because I needed to know whether you missed your father or the financial arrangements.”
He looked down.
“That’s unfair.”
“Maybe. But it’s a question I couldn’t avoid.”
We ordered coffee.
After several minutes, Logan admitted he’d known Chelsea’s treatment of me was wrong.
“I thought staying out of it would keep the peace.”
“It kept peace for you,” I answered. “Not for me.”
His eyes reddened.
“I was embarrassed.”
“Of me?”
“No. Of how we treated you.”
For the first time, I believed he understood something beyond the money.
Then he asked how much I actually had saved.
“That’s private, Logan.”
“But Chelsea says you must have a fortune.”
“The amount doesn’t change what happened at dinner.”
He stared at his coffee.
Before leaving, I told him I loved him, but I would never again finance a lifestyle he couldn’t sustain.
That evening, Logan went home and searched through the old filing cabinet I’d left behind.
Inside was the renovation agreement, several bank statements, and a four-year-old document used when his business credit line was renewed.
He unfolded it beneath the kitchen light.
There, beside my name, was the verified value of my investment portfolio.
$803,417.29.
He read it twice.
Then he noticed the account ownership designation.
Albert Higgins — Sole Owner.
The father he’d treated like a dependent guest had never depended on him at all.
And when Chelsea came downstairs and saw the statement in his hands, Logan finally asked her the question he’d avoided for six years.
“Did you ever stop to wonder how much of our life Dad was paying for?”
Part 3: My Son Found My $800,000 Investment Statement—Then His Wife Learned What Their House Really Cost
Chelsea stood across the kitchen island, staring at the investment statement in Logan’s hand. The number at the bottom of the page seemed to have taken away her ability to speak.
“Eight hundred thousand dollars?” she finally whispered.
Logan nodded.
“That’s what Dad had in investments four years ago.”
Chelsea reached for the document, but he pulled it back.
“Did you know about this?”
“No. I thought he lived on his pension.”
“So did I.”
For several moments, they stood surrounded by the expensive kitchen cabinets, marble countertops, and appliances they’d chosen during the renovation.
Then Logan opened another folder.
“Do you know how much we still owe Dad for this house?”
Chelsea frowned.
“He helped with the renovation.”
“He lent us $186,400.”
Her face changed.
“You said your father wanted to contribute.”
“I said he was helping us. I should have explained that we signed a loan agreement.”
Chelsea lowered herself onto a stool.
“You never told me we had to pay him back.”
“I convinced myself we’d handle it when the business was doing better.”
“But you kept borrowing.”
Logan looked toward the window.
He couldn’t deny it.
His renovation company had grown quickly, but much of that growth depended on borrowed money. Whenever cash flow became difficult, he’d reassured himself that his father’s investments provided a safety net.
Now that protection was disappearing.
“The bank needs replacement collateral,” he said. “If we can’t arrange it, we may have to sell assets or reduce the business debt.”
Chelsea stared at the kitchen.
“Are we going to lose the house?”
“I don’t know.”
For the first time, she seemed to understand that the life she’d defended so fiercely had never been as secure as she’d believed.
The next morning, Logan contacted his lender and began reviewing the company’s finances. He canceled an equipment purchase, postponed an office expansion, and arranged a meeting with a refinancing specialist.
Meanwhile, I was settling into my apartment.
I bought groceries, cooked my own breakfast, and placed Margaret’s photograph beside my bed.
For years, I’d imagined that living with Logan meant preserving our family after her death.
Instead, I’d gradually surrendered the independence she and I had worked so hard to build.
That afternoon, Fiona called.
“Albert, the bank has acknowledged your notice. They’re reviewing Logan’s refinancing options.”
“Good.”
“There’s another matter I’d like to discuss. Your estate plan still lists Logan as the primary beneficiary of your investment account.”
I looked at Margaret’s photograph.
I’d written that designation years earlier, when I assumed my son would eventually inherit everything.
“What would happen if I changed it?”
“Your assets would be distributed according to the revised instructions. We can also discuss charitable giving and a reserve for your future care.”
I remained silent.
Margaret had taught elementary school for thirty-one years. She’d often worried about retired teachers who struggled to afford housing after dedicating their lives to children.
I remembered her saying, “A safe place to live shouldn’t be a luxury after a lifetime of work.”
“Fiona, is there a foundation that helps retired teachers find affordable housing?”
“Several. I can arrange an introduction.”
Over the following days, we met with representatives from a North Texas housing nonprofit.
They explained how donations could support rental assistance, accessibility repairs, and emergency housing for older educators.
For the first time since leaving Logan’s house, I felt excited about something that had nothing to do with my son’s problems.
I asked Fiona to explore establishing a fund in Margaret’s memory.
She prepared a proposal outlining the donation, the money I’d retain for retirement, and the changes to my estate plan.
I hadn’t made a final decision yet.
But I knew one thing: my savings would no longer exist simply to rescue Logan whenever he made another expensive mistake.
Two days later, my son called.
“Dad, Chelsea and I have been talking.”
“I’m listening.”
“We may need to sell the house.”
“I’m sorry it’s come to that.”
“Are you?”
His question stung.
“Logan, I don’t want you to lose your home. But I can’t keep financing it.”
He sighed.
“I know. I’m starting to understand.”
Then he hesitated.
“There’s something else. I found an old beneficiary statement. It says I would inherit your investment account.”
“That was the arrangement when the statement was issued.”
“Was?”
I looked at the charitable proposal resting on my desk.
“I’m reviewing my estate plan.”
His voice became uncertain.
“Dad, what does that mean?”
“It means I’m deciding how to use the money Margaret and I spent our lives earning.”
He didn’t answer immediately.
Finally, he whispered, “Are you cutting me out of your will?”
“I haven’t made my final decisions.”
After we ended the call, Fiona sent me a revised proposal.
At the top was the name we’d chosen.
The Margaret Higgins Teacher Housing Fund.
Beneath it was the proposed initial contribution.
$575,000.
I stared at the figure, remembering how Margaret used to slip grocery money into the hands of struggling retired colleagues.
Then I picked up my pen.
And for the first time in my life, I was ready to make a financial decision without wondering whether my son would approve.
Part 4: I Donated $575,000 Without Telling My Son—Then He Showed Up Asking About His Inheritance
Three days after I approved the donation, my attorney called to confirm that the transfer had been completed.
“Five hundred seventy-five thousand dollars,” Fiona said. “The foundation has acknowledged receipt, and the remaining funds have been allocated according to your retirement plan.”
I sat beside the window of my apartment, holding Margaret’s photograph.
For years, I’d imagined leaving everything to Logan. Now a substantial portion of our savings would help retired teachers find safe, affordable homes.
I wished Margaret could have seen it.
That afternoon, Fiona sent me photographs of the foundation’s renovated brick building near downtown Dallas. Beneath its entrance sign were the words A Home Is More Than a Roof.
The directors had agreed to establish the Margaret Higgins Teacher Housing Fund.
I studied the name for several minutes.
Margaret had spent thirty-one years teaching children whose families sometimes struggled to pay rent. She’d quietly bought winter coats, school supplies, and groceries for students who needed them.
This felt like something she would have understood.
Meanwhile, Logan and Chelsea were confronting a different reality.
Their lender had agreed to consider additional time for refinancing, but Logan needed to reduce the company’s debt and provide a credible repayment plan.
He and Chelsea spent an entire evening reviewing their expenses.
The mortgage.
The vehicles.
The business equipment.
The renovations they’d financed without considering what would happen if my support ended.
“We can’t keep the house and fix everything else,” Logan finally admitted.
Chelsea stared at the figures.
“Then we sell it.”
He looked surprised.
“You love this house.”
“I loved what I thought it represented.”
“What do you mean?”
She looked around their expensive kitchen.
“I thought it meant we’d succeeded. But your father helped pay for almost everything, and we treated him like he was lucky to be here.”
Logan lowered his eyes.
“I should’ve told you how much we owed him.”
“And I should’ve treated him decently whether he had money or not.”
For once, neither tried to excuse the other.
The following morning, Logan discovered an older estate-planning letter among his paperwork. It confirmed that he’d once been the designated beneficiary of my investment account.
He called my sister Miriam, hoping she knew whether I’d changed my plans.
“Your father is meeting with the housing foundation tomorrow,” she told him.
“Why?”
“That’s something you should ask him.”
“Can I see him?”
“He’s asked not to be interrupted during the meeting.”
Logan hesitated.
“Is he giving away his money?”
Miriam wouldn’t discuss my finances.
But she agreed to let Fiona know he wanted to speak with me.
The next morning, Logan and Chelsea arrived at the foundation together.
Fiona greeted them in a second-floor conference room.
“Albert knows you’re here,” she explained. “He’ll join us shortly.”
Chelsea looked nervous.
“Is he willing to talk to me?”
“That’s his decision.”
Fiona placed a folder on the table.
“Before he arrives, I need to clarify the financial arrangements. Albert has authorized me to explain the relevant figures.”
Logan leaned forward.
“The investment account contained approximately $803,000 when we began this process. Albert has since donated $575,000 to establish a housing fund in Margaret’s memory.”
Logan stared at her.
“He gave away more than half a million dollars?”
“Yes.”
“And what’s left?”
“Approximately $214,000 remains in the investment portfolio after the transfer and associated adjustments. He also has his pension and other retirement resources.”
Chelsea folded her hands tightly.
“Will he have enough to live on?”
“His financial plan provides for his anticipated needs. He reviewed it carefully before making the donation.”
Logan looked toward the window.
For years, he’d assumed his father’s savings would eventually become his inheritance.
Now he understood that I’d made another choice.
“What about the money we owe him?”
“The $186,400 loan remains outstanding,” Fiona answered. “Albert is willing to restructure repayment over five years at a reduced interest rate.”
Chelsea exhaled.
“We’re planning to sell the house.”
“That may allow you to repay the loan sooner.”
“And my business?”
“The bank has extended the deadline to sixty days. You’ll still need replacement financing or a substantial reduction in the balance.”
Logan nodded slowly.
Then he asked the question he’d been avoiding.
“Did Dad disinherit me?”
Fiona shook her head.
“He’s revised his estate plan to protect his independence. You remain included, but you no longer have automatic access to the investment account upon his death.”
Logan sat back.
“I thought he was trying to teach me a lesson.”
“The donation wasn’t about you,” Fiona said. “It was about what Albert wanted to do with his own life.”
The conference room door opened.
I stepped inside wearing my old gray jacket and the leather shoes Chelsea had once called embarrassing.
Logan stood immediately.
“Dad.”
“Hello, son.”
Chelsea rose beside him.
“Albert, may I say something?”
I nodded.
Her eyes filled with tears.
“I’m sorry I made you feel unwelcome. I told you to hide in your room, and I humiliated you in front of people who were guests in your home.”
I waited.
She continued without making excuses.
“I treated your generosity as something I deserved. You didn’t deserve any of that.”
Then Logan stepped forward.
“Dad, I knew she was hurting you. I saw it happening, and I chose not to get involved.”
His voice cracked.
“When you needed me to defend you, I looked away.”
I felt my throat tighten.
“That was the part that hurt most.”
“I know,” he whispered.
“I never wanted you to choose between your wife and your father, Logan. I wanted you to recognize when something was wrong.”
He nodded, wiping his eyes.
For the first time, I believed we might have a chance to repair what had happened.
Then Logan looked at the folder on the table.
“Dad, Chelsea and I have decided to sell the house. We want to repay what we owe you.”
I reached for his hand.
“Then perhaps we’re finally ready to begin again.”
But before Fiona could prepare the revised agreement, Logan asked one final question.
“Dad, when the money is gone and the house is sold, will you still want us in your life?”
Part 5: My Son Finally Apologized for Throwing Me Out—But I Had One Last Decision to Make
My son stood across from me in the foundation’s conference room, his eyes filled with tears.
“Dad, when the money is gone and the house is sold, will you still want us in your life?”
For a moment, I couldn’t answer.
I remembered Logan at seven years old, running through our backyard with scraped knees, calling for me whenever something frightened him. I remembered teaching him to ride a bicycle while Margaret watched from the porch.
Somewhere along the way, we’d stopped being father and son and become two men who were afraid to disappoint each other.
“Logan,” I finally said, “I never stopped wanting you in my life.”
He lowered his head.
“But I can’t keep buying my place in yours.”
He looked up.
“I understand.”
“I hope you do, because things are going to be different.”
I explained that I wouldn’t move back into their house, cover their expenses, or pledge my investments to support his company again.
I would offer advice when he asked for it, but the decisions and consequences would belong to him.
Chelsea nodded.
“That’s fair, Albert.”
I turned toward her.
“And I need time before things feel comfortable between us again.”
“I know,” she replied. “I don’t expect you to forgive me just because I apologized.”
That answer mattered more than she probably realized.
Fiona placed the revised loan agreement on the table. It provided a five-year repayment schedule at a reduced interest rate, with an option to repay the remaining balance when their house sold.
Logan read every page.
When he reached a section he didn’t understand, he asked Fiona to explain it.
I almost smiled.
For years, he’d signed financial documents while assuming I would protect him from whatever he’d overlooked.
This time, he was taking responsibility.
He signed the agreement.
Chelsea signed the acknowledgment beside him.
And for the first time, I didn’t feel obligated to rescue either of them.
Three months later, their house sold.
The proceeds allowed them to repay my family loan and reduce the renovation company’s debt enough to arrange refinancing without my investments as collateral.
They moved into a smaller home near Logan’s office.
It had an ordinary kitchen, a modest backyard, and no impressive dining room for entertaining important guests.
But they could afford it.
Meanwhile, I moved into an independent-living apartment overlooking a sunny courtyard.
I bought a comfortable reading chair, hung Margaret’s photograph above my desk, and started volunteering with the housing foundation.
The first time I attended a meeting about the Margaret Higgins Teacher Housing Fund, I met a retired elementary school teacher named Dorothy.
She had spent thirty-eight years teaching children but had recently struggled to afford an accessible apartment after an unexpected medical expense.
The foundation was helping her remain safely housed.
When Dorothy learned whose name was attached to the fund, she took my hand.
“Your wife must have been a remarkable woman.”
I smiled.
“She was.”
That evening, I sat beside Margaret’s photograph and cried.
Not because I regretted the donation.
Because, for the first time since her death, I’d found a way to honor her that didn’t require sacrificing my own happiness.
Every other Sunday, Logan began visiting my apartment.
Sometimes he brought groceries. Sometimes Chelsea came with him, carrying homemade bread or flowers for the small table beside my window.
Nobody asked me for money.
Nobody mentioned inheritance.
At first, our conversations were awkward. Apologies couldn’t erase six years of resentment, and I wasn’t interested in pretending otherwise.
But slowly, we learned how to speak honestly.
One afternoon, Logan brought a folder containing his company’s revised financial plan.
“Dad, would you mind looking at this?”
I raised an eyebrow.
“Are you asking me to finance it?”
He laughed.
“No. I want your opinion, not your money.”
“Then sit down.”
We spent an hour reviewing his projections.
He’d reduced unnecessary expenses, renegotiated supplier agreements, and established an emergency reserve for the business.
For the first time, his plans didn’t depend on someone else absorbing the risk.
“I’m proud of the work you’ve done,” I told him.
He looked genuinely surprised.
“Really?”
“Really.”
He smiled, and for a moment, I saw the boy who used to run home waving his report card.
Later that afternoon, Chelsea arrived with a container of homemade soup.
She paused at the doorway.
“Albert, I hope I’m not interrupting.”
“You’re not.”
She placed the soup on the counter.
“I made too much. I thought you might like some.”
I thanked her.
Then she looked toward Margaret’s photograph.
“Logan told me about the housing fund. I think she would have loved it.”
I followed her gaze.
“She would have wanted to meet every teacher it helped.”
Chelsea smiled.
“I wish I’d known her better.”
“So do I.”
We stood quietly for a moment.
There were still things we hadn’t resolved, but we no longer needed to pretend everything was fine.
When Logan began gathering his papers, I glanced at the clock.
“Are you two busy tonight?”
He shook his head.
“Why?”
“I made vegetable soup this morning. There’s enough for three.”
Logan looked at me.
“Are you sure, Dad?”
I thought about that dinner months earlier, when Chelsea had ordered me upstairs and my son had remained silent.
I remembered leaving my key on the kitchen counter, convinced I would never feel welcome with them again.
Now we were standing in my apartment, where nobody had the power to tell me I didn’t belong.
“Yes,” I said. “I’d like you both to stay.”
Chelsea helped set the table while Logan warmed the bread.
We ate beside the window as the evening sunlight stretched across the courtyard.
Nobody discussed money.
Nobody asked about my investments.
We talked about Logan’s business, Chelsea’s work, and a gardening project the foundation was organizing for retired teachers.
At one point, Logan looked around my apartment.
“You seem happy here, Dad.”
“I am.”
He nodded thoughtfully.
“I think I finally understand why you left.”
I set down my spoon.
“Tell me.”
“You weren’t trying to hurt us. You were trying to stop hurting yourself.”
My throat tightened.
“That’s exactly right.”
He reached across the table and squeezed my hand.
“I’m glad you did.”
Later, after they left, I washed the dishes and placed the leftovers in the refrigerator.
Then I sat beside Margaret’s photograph.
For years, I’d believed that being a good father meant giving my son everything I could, even when it cost me my dignity.
But love wasn’t supposed to leave one person empty so another could remain comfortable.
My son hadn’t lost his father when I walked away.
He’d finally been given the chance to know me as a person, not a source of money.
And I hadn’t lost my family.
I’d simply stopped paying for the privilege of belonging to it.
I looked at Margaret’s smiling face and whispered, “I think we’re going to be all right.”
Outside, the courtyard lights came on one by one.
For the first time in six years, I didn’t wonder whether I was welcome somewhere.
I was home. And this time, I belonged there because I chose to.